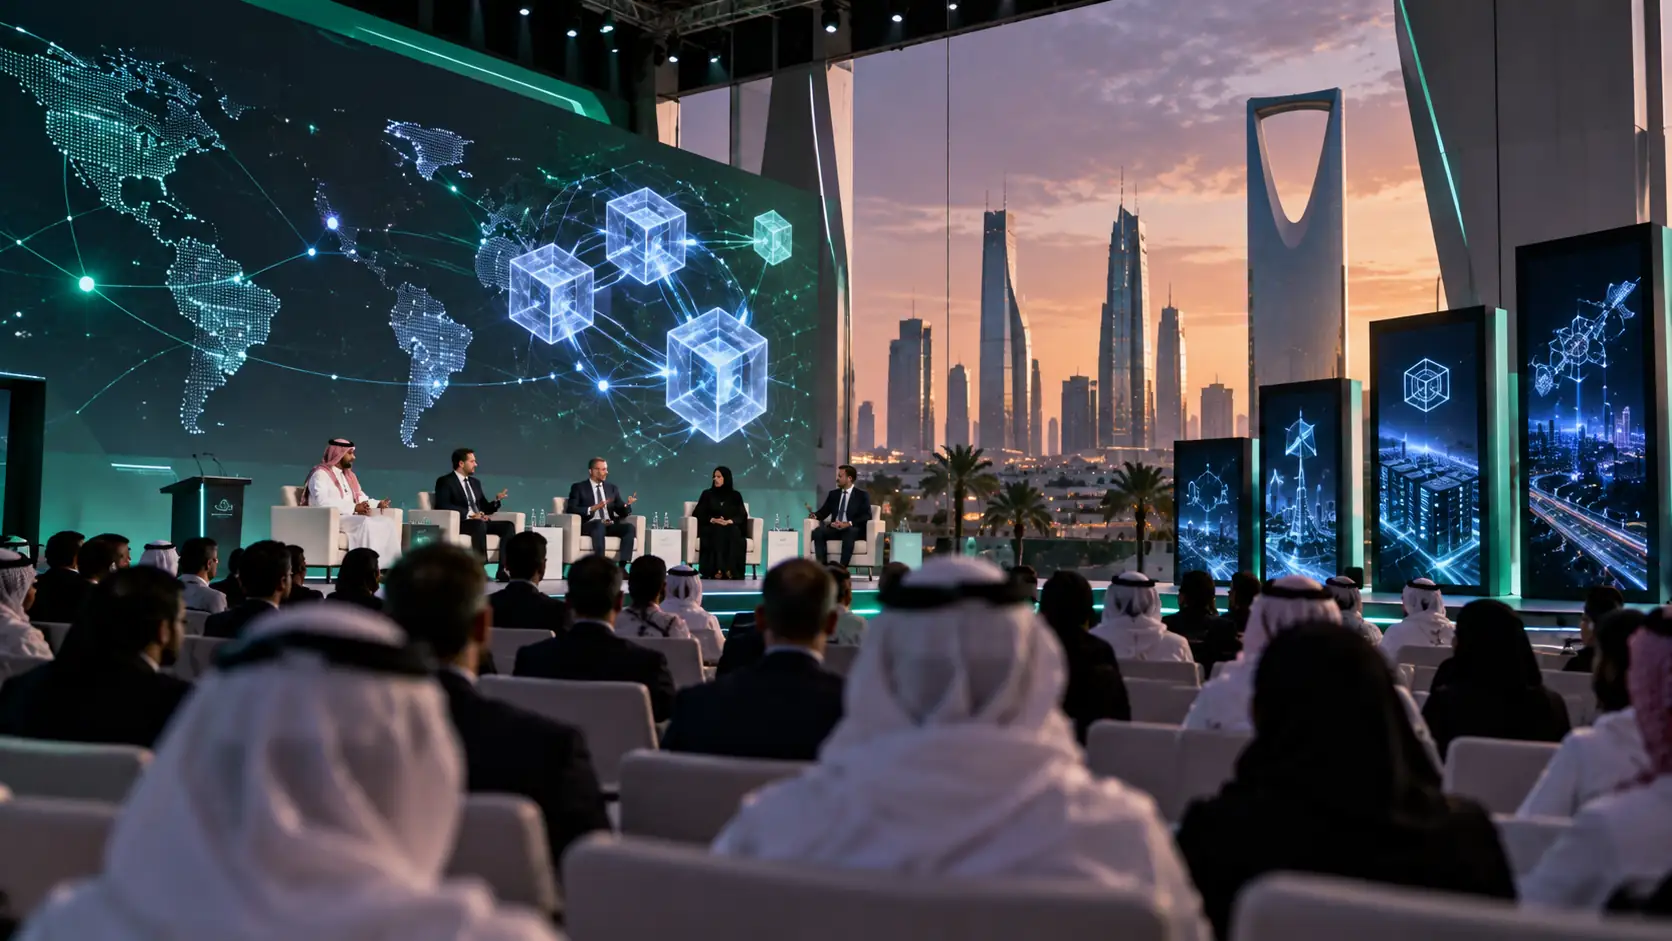
The Global Blockchain Show Riyadh 2026 concluded with a noticeably different message from the crypto conferences built around token speculation and short-term market cycles. Across two days in Saudi Arabia, discussion concentrated on the less glamorous infrastructure required to make blockchain useful at business scale: chain abstraction, digital identity, tokenization, interoperability, cybersecurity, decentralized finance and increasingly, the integration of blockchain with artificial intelligence.
Held on June 29–30 and organized by VAP Group with Times of Blockchain, the event reported more than 15,000 registrations and 6,723 attendees, alongside 100+ speakers and 100 exhibitors. Organizers said delegates represented more than 80 countries and roughly 70% of the audience held C-level positions, although those attendance and demographic figures are organizer-reported rather than independently audited.
Those numbers provide scale, but the more significant signal came from the agenda. Web3 companies are increasingly trying to hide blockchain’s technical complexity from end users while demonstrating that decentralized infrastructure can solve practical problems involving finance, ownership, identity, data provenance and automation. Riyadh offered a snapshot of that transition.
Global Blockchain Show Moved From a Preview to a 6,723-Attendee Event
Before the conference, organizers projected more than 10,000 delegates for the Riyadh edition following previous Global Blockchain Show events in Dubai and Abu Dhabi. The completed event produced a more precise picture: 15,000+ registrations translated into 6,723 reported attendees over the two-day program.
The event was co-located with the Global AI Show and Global Games Show, creating substantial overlap between blockchain, artificial intelligence and digital entertainment. That structure helped move the conversation beyond cryptocurrencies because many of the technical problems discussed—identity, data ownership, provenance, payments and automated transactions—cut across all three sectors.
Speakers came from blockchain companies, financial services, cybersecurity, enterprise technology, academia and the wider digital-asset ecosystem. The program included representatives such as Meow, co-founder of Jupiter; Shabir Momin, president and founder of TorusChain; Ulysses Demos, Chief Global Data Officer at Red Sea Global; and Billal Yamak, chairman and co-founder of the Web3 Alliance of Saudi Arabia.
The breadth of those participants reflected the event’s larger theme: blockchain developers increasingly need to connect decentralized technology with businesses and institutions operating outside crypto-native markets.
Chain Abstraction Emerged as a Key Infrastructure Theme
One of the more technically important subjects in Riyadh was chain abstraction.
Blockchain users currently face a fragmented environment of different networks, wallets, bridges, gas tokens and transaction rules. Someone moving assets between ecosystems may need to understand which blockchain holds an asset, which network is being used, how transaction fees are paid and whether a bridge is required.
That complexity is manageable for experienced crypto users but creates friction for mainstream adoption.
Chain abstraction attempts to hide some of those differences. Instead of forcing users to understand the technical architecture underneath every transaction, applications can handle network selection, routing and other blockchain-specific processes behind the interface.
The idea resembles what happened to the internet. Most people using an online service do not need to understand TCP/IP, DNS routing or the physical location of a server. Those technologies remain essential, but successful applications conceal much of the infrastructure. Web3 developers increasingly want blockchain to work the same way.
“Invisible Blockchain” Could Matter More Than Blockchain Branding
That leads to another theme highlighted at the conference: the idea of invisible blockchain.
For years, blockchain products frequently marketed the underlying technology as part of the consumer proposition. Users were expected to create wallets, manage seed phrases, acquire tokens for transaction fees and understand which network an application used. That approach limited the potential audience.
If blockchain is to become infrastructure for mainstream applications, users may eventually interact with decentralized systems without consciously thinking about blockchains at all. Gasless transactions, embedded wallets, account abstraction and simplified onboarding can move technical complexity into the background.
The important question then becomes whether blockchain provides a measurable advantage—such as programmable ownership, transparent settlement, verifiable records or interoperability—rather than whether consumers are excited about using “Web3.”
That represents a meaningful change in product thinking. Successful enterprise blockchain may ultimately become less visible, not more.
Tokenization Is Moving Closer to Traditional Finance
Tokenization was another major topic in Riyadh and is becoming one of the clearest bridges between conventional finance and blockchain infrastructure.
At its simplest, tokenization represents rights to an asset digitally on a programmable ledger. Those assets can range from financial securities and funds to commodities or other forms of ownership.
The potential advantage is not simply converting an asset into a token. Programmable infrastructure can change how ownership is transferred, how transactions settle and how different financial products interact.
That is why tokenization increasingly attracts interest from banks, asset managers and financial regulators rather than only cryptocurrency companies.
The difficult part remains regulation. A token representing a security does not stop being economically equivalent to a security simply because blockchain technology is used. Questions around custody, investor protection, ownership rights, compliance and settlement remain fundamental.
Saudi Arabia’s financial regulators have already created environments for testing emerging financial technologies. The country’s Capital Market Authority, for example, includes the use of distributed-ledger technology for arranging and offering securities and custody services among categories represented in its FinTech experimental-permit framework.
That makes Riyadh a particularly relevant location for discussions about where blockchain infrastructure meets regulated finance.
Saudi Arabia’s Fintech Market Provides Important Context
The Global Blockchain Show also took place against a much broader expansion of Saudi Arabia’s digital-finance ecosystem.
According to the Saudi Vision 2030 Annual Report 2025, the number of fintech companies in the Kingdom increased from 20 to 301, while digital payments rose from 18% to 85% of retail transactions. The report attributes that expansion to the country’s fintech strategy, regulatory development and initiatives including Fintech Saudi.
Those figures do not mean Saudi Arabia has adopted decentralized finance wholesale. The country’s regulated fintech expansion is much broader than cryptocurrency or Web3.
But it does explain why blockchain companies see the Kingdom as an important market.
A financial system already moving toward digital payments, digital banks, automated services and experimental regulatory frameworks provides a more plausible environment for blockchain-based infrastructure than one still dependent predominantly on cash and manual processes.
For Web3 companies, the opportunity is therefore less about persuading consumers to speculate on tokens and more about demonstrating where decentralized infrastructure can complement a rapidly digitizing financial sector.
AI and Blockchain Are Beginning to Share Infrastructure Problems
Co-locating the Global Blockchain Show with the Global AI Show also highlighted a growing intersection between two technology sectors that are often discussed separately.
AI systems need enormous quantities of data. As autonomous AI agents become more capable, they may also need mechanisms for identity, authorization, payments and verification.
Blockchain advocates argue that decentralized infrastructure can potentially provide some of those mechanisms.
For example, cryptographic records could help establish where particular data originated or document transactions performed by autonomous systems. Smart contracts could allow software agents to interact with programmable financial infrastructure, while digital identity systems could help establish which agent or organization is authorized to perform an action.
None of this means blockchain is inherently required for AI. Conventional databases, identity systems and payment networks already solve many of these problems effectively.
The more credible opportunity lies in cases where multiple parties need to coordinate without relying entirely on one organization’s database. That is where verifiable shared records and programmable digital assets can become more useful.
AI Also Creates a New Problem: Proving What Is Real
The convergence becomes particularly interesting around digital provenance.
Generative AI has made it dramatically easier to produce convincing text, images, audio and video. As synthetic content becomes harder to distinguish from authentic material, systems that can establish where information originated become more valuable.
Blockchain cannot determine whether a photograph depicts reality simply by recording it. If false information enters a ledger, immutability does not magically make the information true.
What decentralized systems can potentially provide is a tamper-resistant record showing when information was registered, which identity registered it and whether it has subsequently been altered.
That makes blockchain potentially useful as one component of a wider provenance architecture involving cryptographic signatures, trusted hardware and content-authentication standards.
The distinction is important. Blockchain is not an automatic solution to AI-generated misinformation, but the AI era is creating new demand for verifiable digital records.
Cybersecurity Remains a Major Barrier to Web3 Adoption
The Riyadh program also emphasized cybersecurity, an unavoidable subject for a sector in which software vulnerabilities can translate directly into financial losses.
Traditional applications can sometimes reverse fraudulent transactions or restore data from backups. Blockchain systems can make recovery more difficult because transactions may be irreversible and digital assets can move rapidly across multiple addresses or networks.
Smart-contract vulnerabilities, compromised private keys, phishing attacks, insecure bridges and weak wallet security have repeatedly exposed those risks.
Enterprise adoption therefore requires more than faster blockchains. Companies need secure key management, identity controls, smart-contract auditing, monitoring and procedures for responding when systems fail.
The move toward chain abstraction can create additional security questions. Hiding complexity improves usability, but the infrastructure performing routing, bridging and transaction execution must itself be trustworthy. Web3’s usability problem and its security problem are therefore increasingly connected.
DeFi Is Looking for a Route Toward Institutional Finance
Decentralized finance also remained an important part of the event, but the discussion increasingly centered on coexistence with traditional financial institutions rather than replacing them.
DeFi demonstrated that financial transactions such as trading, lending and asset exchange can be implemented through programmable protocols. The sector also demonstrated the risks of that model through hacks, unstable economic designs and periods of extreme speculation.
The next phase is likely to depend on whether useful elements of decentralized finance can operate within regulatory frameworks acceptable to institutional participants.
That could mean permissioned environments, tokenized regulated assets, stronger identity mechanisms or blockchain settlement infrastructure integrated with conventional financial institutions.
Such systems may look less ideologically decentralized than early DeFi applications. They could nevertheless bring parts of blockchain architecture into much larger financial markets.
The distinction between “traditional finance” and “DeFi” may consequently become less clear if regulated financial products increasingly use programmable infrastructure underneath conventional customer interfaces.
VAP Ventures Added an Investment Dimension
The conference also included the launch of VAP Ventures, an initiative from event organizer VAP Group that says it intends to support 100 startups by 2030 across blockchain, AI, gaming and related emerging technologies.
The target should be treated as an announced ambition rather than an achieved investment result. Details such as investment size, selection criteria, ownership structure and the amount of committed capital will ultimately determine how significant the initiative becomes. Still, its launch reinforces a broader theme surrounding the Riyadh events.
Conferences increasingly compete not simply by assembling speakers but by connecting startups with capital, corporate customers and government ecosystems. That is particularly relevant in emerging technology sectors where young companies need regulatory access and enterprise partnerships as much as venture financing.
Whether VAP Ventures produces meaningful companies will become measurable only over the next several years.
Riyadh Is Becoming a Meeting Point for Emerging Technology
Saudi Arabia’s interest in hosting blockchain, AI and gaming events simultaneously also fits its wider economic diversification strategy.
The Kingdom is investing heavily in digital infrastructure, artificial intelligence, gaming, fintech and technology entrepreneurship as it attempts to expand economic activity beyond oil.
That does not mean every technology promoted at conferences in Riyadh will achieve large-scale domestic adoption. Event activity and commercial deployment are different measurements.
But the combination of government-backed digitalization, capital availability and large technology events is helping Riyadh attract companies looking for customers and investors across the Middle East.
For blockchain companies in particular, that provides an alternative growth narrative to the industry’s historic concentration around cryptocurrency trading. The opportunity is increasingly enterprise infrastructure.
Web3 Still Has to Prove Its Business Case
The Global Blockchain Show’s shift toward infrastructure does not eliminate the central challenge facing blockchain technology.
Companies still need to demonstrate where decentralized systems outperform conventional alternatives.
A traditional database is cheaper and simpler for many applications. If one organization controls the information and every participant trusts that organization, adding a blockchain can create unnecessary technical complexity.
Blockchain becomes more compelling when multiple parties need to coordinate, ownership needs to be programmable, records need to be independently verifiable or users need to transact without placing complete control in one intermediary.
Those distinctions matter because the industry spent years applying blockchain terminology to projects that did not necessarily require decentralized infrastructure.
Enterprise adoption will ultimately depend less on how many organizations say they are experimenting with Web3 and more on whether deployments reduce costs, improve settlement, create new markets or solve coordination problems that existing technology handles poorly.
Global Blockchain Show 2026 Reflected a More Infrastructure-Focused Web3
The pre-event narrative around Global Blockchain Show Riyadh emphasized bringing global technology leaders together to shape blockchain’s future. The completed event produced a more useful conclusion. The blockchain industry’s priorities are changing.
Chain abstraction and gasless transactions aim to remove technical friction. Tokenization is bringing blockchain closer to conventional financial markets. Digital identity and provenance are becoming more relevant as AI complicates online trust. Cybersecurity remains fundamental, while the combination of AI agents and programmable financial infrastructure is opening another area for experimentation.
None of those developments guarantees mass blockchain adoption. They do, however, show an industry trying to move beyond the assumption that users should care about blockchain simply because an application uses it.
If the next generation of Web3 succeeds, many users may barely notice the blockchain underneath their applications.
For an industry that spent years putting blockchain at the center of its marketing, becoming invisible may ultimately be one of its most important signs of maturity.