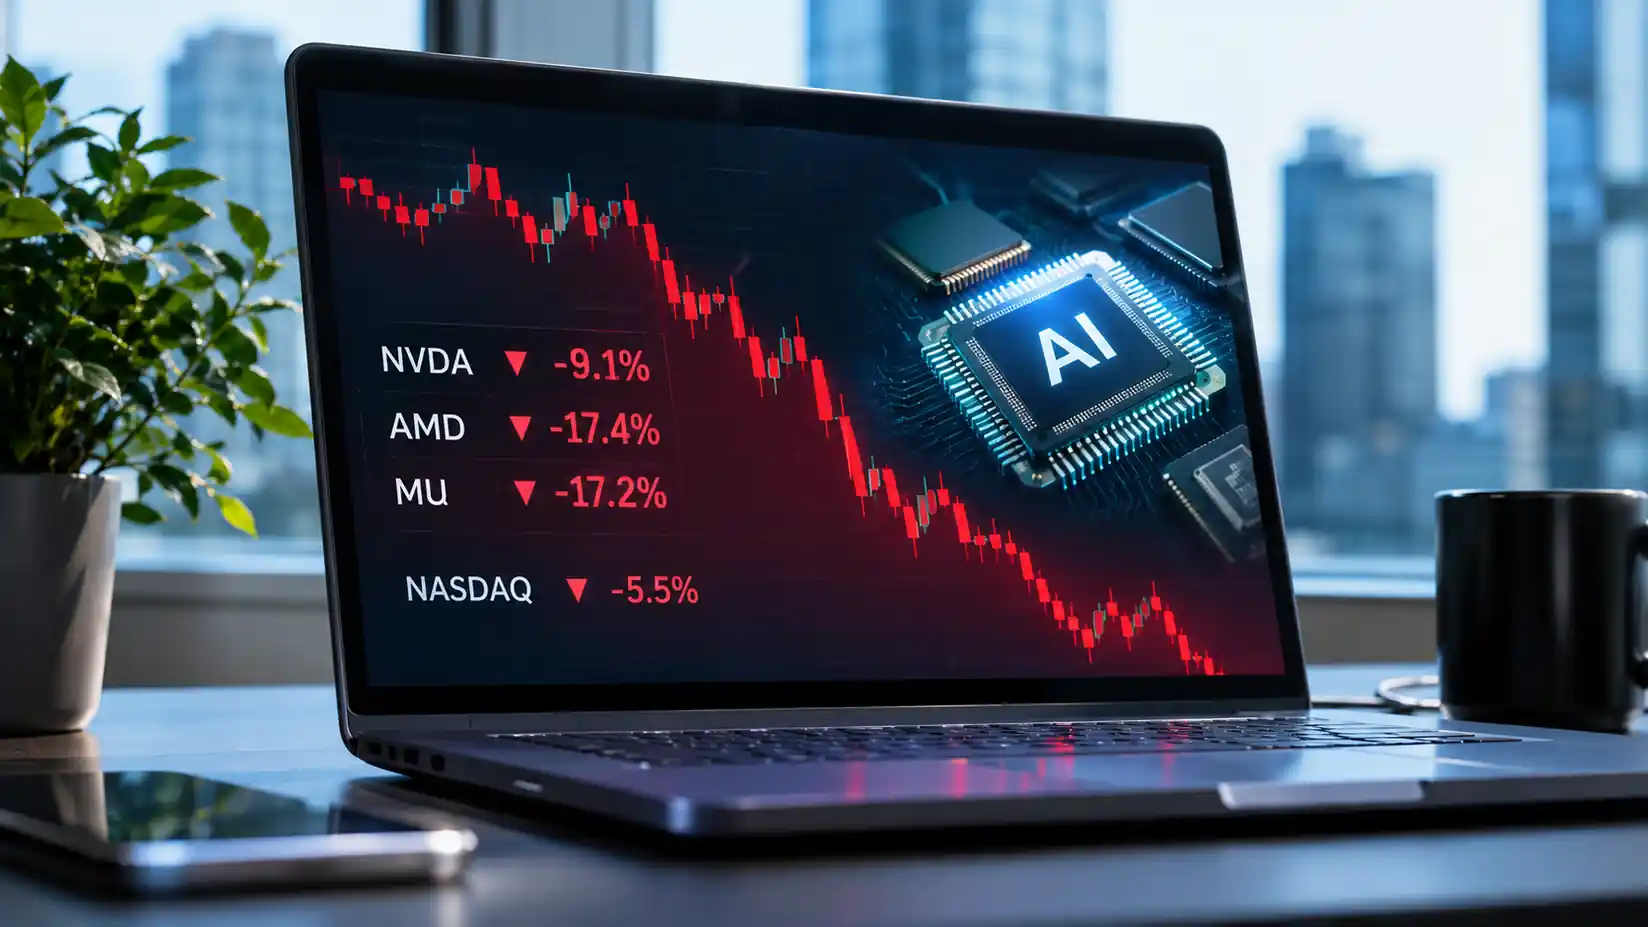
The global AI stock sell-off in early November 2026 wiped billions of dollars from major technology companies as investors questioned soaring infrastructure costs and stretched valuations. On Nov. 5, Nvidia shares plunged more than 9%, while AMD and Micron Technology each fell over 17%, dragging the Nasdaq Composite down approximately 5.5%.
Although AI stocks partially recovered on Nov. 6, the Nasdaq still ended the week 3.4% lower. The volatility exposed a growing concern across Wall Street: whether the billions invested in AI chips, data centers and computing infrastructure can generate profits substantial enough to justify their valuations.
The AI adoption globally continues across businesses and industries, the economics of building and operating large-scale AI infrastructure remain under scrutiny.
The central question is no longer simply whether artificial intelligence will transform business operations. It is whether companies investing billions of dollars in computing infrastructure can generate sustainable returns that justify their valuations.
Why AI Stocks Are Becoming More Sensitive to Investment Expectations
AI-related stocks have benefited from expectations that demand for advanced computing will continue expanding.
Nvidia, AMD, Micron Technology and other semiconductor companies supply essential components for AI data centers, cloud computing and machine learning workloads.
Their commercial opportunities are connected to spending by major technology companies developing AI models, enterprise services and digital infrastructure.
However, the relationship between infrastructure demand and investment returns is not straightforward.
Strong demand for AI chips can support semiconductor revenue even when the companies purchasing those chips face uncertainty about the profitability of their own AI products.
This creates different financial risks across the AI value chain.
Chipmakers may benefit from immediate hardware orders, while cloud providers and AI developers must recover their investments through services, subscriptions, enterprise contracts or other revenue models.
The November market volatility suggests investors are paying closer attention to these distinctions.
A company can participate in a rapidly growing industry without necessarily delivering the financial performance implied by its stock valuation.
The AI Infrastructure Boom Has a Capital Efficiency Problem
One of the defining characteristics of the current AI investment cycle is its dependence on expensive physical infrastructure.
Training and operating advanced AI systems requires specialized processors, networking equipment, memory, data centers and substantial electricity capacity.
These investments create significant upfront costs.
Unlike software products that can sometimes expand with relatively modest additional infrastructure, large-scale AI services require continuous spending on computing resources.
That spending does not end when a data center becomes operational.
Operators must account for maintenance, electricity, cooling, equipment replacement and the possibility that newer hardware will make existing systems less economically competitive.
The financial challenge is therefore not simply building enough AI infrastructure. It is ensuring that the infrastructure generates sufficient economic value throughout its useful life.
The Gignomist previously examined the scale of this investment cycle in its reporting on Alphabet’s $32 billion debt raise to finance AI expansion.
Large financing commitments demonstrate how central AI has become to corporate strategy. They do not, by themselves, establish that every investment will deliver attractive returns.
For investors, several financial measures are becoming particularly relevant: capital expenditure relative to revenue, operating cash flow, infrastructure utilization and the time required to recover investment costs.
A business with growing AI revenue may still face financial pressure if the cost of supporting that growth increases at a similar or faster rate.
AI Adoption and AI Profitability Are Different Questions
The distinction between adoption and profitability is essential to understanding AI market valuations.
Businesses can integrate AI into customer service, software development, analytics and administrative workflows without every application producing substantial new revenue.
Some deployments primarily reduce operating costs. Others improve existing products, while certain applications create entirely new services.
Each model has different financial implications.
For example, an enterprise AI tool that reduces employee workload may generate measurable productivity improvements without creating a separate revenue stream.
A consumer-facing AI service, meanwhile, may attract millions of users while struggling to convert usage into subscription income sufficient to cover computing costs.
An AI infrastructure provider faces another challenge: maintaining high utilization of expensive equipment while responding to changing customer requirements.
These differences make it difficult to evaluate the entire AI industry using a single growth narrative.
The more useful approach is to examine where economic value is created, who captures that value and how much capital is required to sustain it.
Why Semiconductor Companies Face Different Risks
Nvidia, AMD and Micron are frequently grouped together as beneficiaries of AI infrastructure investment.
Their exposure to the industry, however, differs.
Nvidia supplies GPUs and associated computing infrastructure used extensively in AI workloads. AMD competes in data center processors and AI accelerators, while Micron supplies memory products essential to high-performance computing.
Their revenue opportunities depend on different combinations of product demand, pricing, manufacturing capacity and customer investment.
This means a slowdown in AI infrastructure spending would not necessarily affect every semiconductor company equally.
Companies with stronger pricing power, differentiated technology or diversified customers may be better positioned than suppliers facing more intense competition.
Investors must also distinguish between temporary demand fluctuations and structural changes in the computing market.
A short-term reduction in orders does not automatically indicate declining long-term demand for AI.
Conversely, strong current sales do not guarantee that customers will continue increasing capital expenditure indefinitely.
The November sell-off and rebound highlight the difficulty of valuing businesses whose future earnings depend partly on investment decisions made elsewhere in the technology ecosystem.
Regulation Could Become an Important Infrastructure Cost
Financial uncertainty is not the only challenge facing AI infrastructure expansion.
The accelerating growth of data center infrastructure raises concerns about electricity demand, water consumption, local infrastructure capacity and environmental effects.
These concerns can influence planning approvals, utility agreements and construction schedules.
The November 2026 US midterm elections added another dimension to the policy discussion, with potential implications for oversight of AI development and supporting infrastructure.
However, political changes should not be confused with enacted regulation.
The investment implications depend on which proposals become law, how they are implemented and whether they materially affect project costs or deployment timelines.
For infrastructure developers, regulatory uncertainty can complicate long-term financial planning.
A delayed project may incur additional financing costs, while restrictions on energy or water availability can affect site selection and operational economics.
At the same time, clearer regulatory standards could reduce uncertainty by establishing predictable requirements for infrastructure development.
The financial consequences will depend on policy design rather than regulation alone.
What the November Sell-Off Reveals About AI Valuations
The early November market decline provides a useful example of how expectations influence technology stock prices.
According to Reuters‘ November 6 market coverage, semiconductor shares recovered some of their earlier losses as investors reassessed the technology sector.
The Nasdaq finished Friday approximately 1.1% higher, but remained down about 3.4% for the week.
A partial recovery does not establish that concerns about AI valuations have disappeared.
Financial markets often react to changes in expectations rather than immediate changes in company operations.
If investors previously anticipated exceptionally rapid revenue growth, even a modest reduction in those expectations can produce a substantial valuation adjustment.
This is particularly relevant for companies trading at prices that already assume years of strong future earnings.
The important distinction is between a business becoming less valuable because its fundamentals have deteriorated and a stock becoming cheaper because investors are less willing to pay for anticipated growth.
Those outcomes can occur together, but they are not identical.
Economic Conditions Add Another Layer of Uncertainty
AI investment also operates within the broader economic environment.
Interest rates, financing costs, employment conditions and business confidence can influence technology spending and equity valuations.
The US Bureau of Labor Statistics’ October 2026 employment report provides one measure of broader economic conditions, separate from the financial performance of individual AI companies.
For capital-intensive businesses, financing costs can be especially important.
Higher borrowing costs may reduce the attractiveness of projects whose financial returns are expected several years into the future.
A weaker economic environment could also cause enterprise customers to delay software purchases or infrastructure commitments.
However, AI spending may prove more resilient in applications where companies can demonstrate measurable cost savings or productivity improvements.
The outcome will depend on how essential AI becomes to business operations and how clearly those benefits can be quantified.
The Next Phase of AI Investment Will Be Defined by Financial Discipline
The AI industry is entering a period in which technological progress and financial performance will increasingly need to be evaluated separately.
Advances in model capabilities, computing efficiency and automation can continue even during periods of stock market weakness.
But investors are likely to demand clearer evidence that these advances translate into sustainable business economics.
Several questions will determine how companies perform through the next stage of AI investment.
Can cloud providers increase revenue faster than infrastructure costs? Can AI developers reduce the computing expense of delivering their services? Will enterprises continue expanding AI budgets after initial deployments? And can semiconductor suppliers maintain strong margins as competition increases?
These questions are more meaningful than short-term changes in share prices because they concern the industry’s ability to generate lasting economic value.
The November 2026 market volatility should therefore be understood as a reassessment of AI investment expectations rather than evidence that the technology’s commercial potential has disappeared.
The defining challenge for the next phase of the AI boom is not proving that artificial intelligence is useful. It is proving that the infrastructure, products and companies supporting it can consistently create more economic value than they consume.